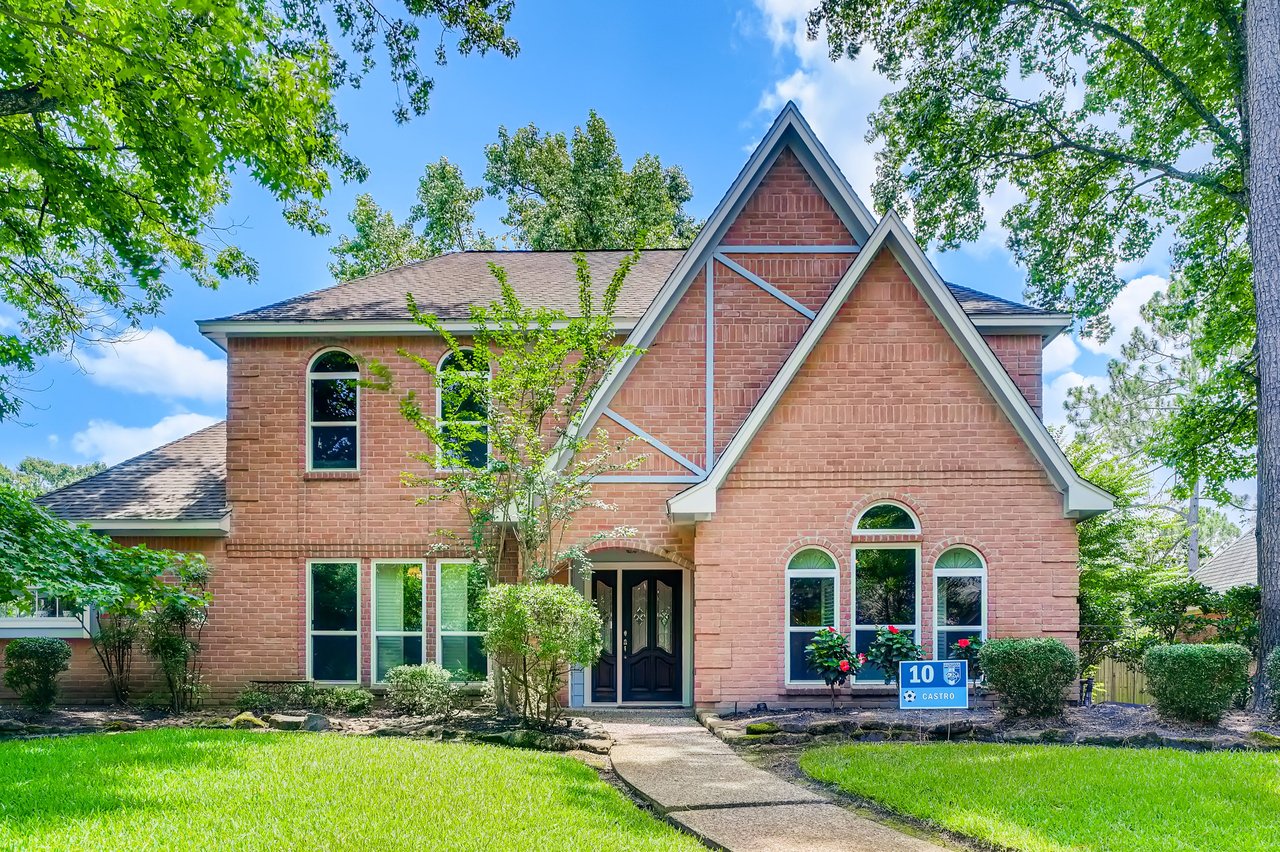
I do. I'm a Naperville agent who works with luxury buyers and sellers, and I handle buying, selling and home valuation. What makes a high-end sale different is not the price tag. It is how the home gets valued, how the buyer's financing works once the loan is above the conforming limit, and how much care goes into presenting and negotiating a one-of-a-kind property. This page covers how I work in that part of the market and what the money side looks like, so you can judge any agent you speak to against it.
What does an agent who sells luxury homes in Naperville actually do differently?
Mostly, the work is slower and more detailed. Higher-end homes are less alike than ordinary ones, so there are fewer clean comparisons, and the price has to be argued from the specifics: the lot, the build quality, the updates, the layout and how the home lives day to day. When I value a home, I explain the reasoning in plain terms, so a seller can see why a number is what it is and decide how to use it.
For sellers, that means honest valuation first, then preparation and presentation that fit the home, then careful handling of showings and offers. For buyers, it means learning what you actually want, which is often less obvious than the list of features, and then looking at homes with a clear eye for what will matter after you move in and what will matter when you someday sell.
How does financing change when a home is high-end?
Many luxury purchases need a jumbo loan, which is a mortgage above the conforming limit set each year by the Federal Housing Finance Agency. The baseline limit for a one-unit home is currently $832,750, and designated high-cost areas get a higher ceiling of $1,249,125. The limit is set by county, and Naperville sits across more than one, so ask your lender which figure applies to the property you are considering.
Jumbo requirements are stricter. The lenders I read describe credit scores typically in the range of 680 to 700 or higher, and some quote 700 to 740. Down payments are often 10% to 20% or more, debt-to-income ratios are commonly capped somewhere between 43% and 50%, and reserves, meaning cash left after closing, can run from six to twelve months of housing payments. Rates on jumbo loans have been quoted as running somewhat above conforming rates.
In practice, I want a buyer talking to a lender before we tour anything serious. Your own numbers depend on your finances and on the lender, so that conversation settles what you can actually bid. It also means your offer carries weight when a seller is deciding between buyers.
How do you value a luxury home when there are few comparable sales?
Pricing a distinctive home is part data and part judgment. I look at what has sold that is genuinely similar, then adjust for what differs, and I am open about where the comparisons are thin. A valuation is a starting point for a decision, not a verdict, and a seller should hear both the strengths and the weak spots.
This matters on the buying side too. Lenders order an appraisal, and on a one-of-a-kind home it can come in below the contract price. We talk through that risk before an offer goes in, including how much cash you would be willing to bring if it happens and what the contract should say.
What can I expect when we work together?
Expect straight answers, including ones you may not want to hear. I explain what an inspection is for, what each contingency protects, and what happens between accepted offer and closing, so nothing arrives as a surprise. Luxury buyers and sellers tend to be busy, so I keep communication clear and organized and let you decide how much detail you want.
I do not push a particular outcome. If waiting is the better move, I will say so. If the home is priced too high or too low, I will explain why. That approach applies whether you are buying your next home, selling a current one, or only trying to understand what your home is worth.
Questions people ask
What is a jumbo loan, and do I need one to buy a luxury home?
A jumbo loan is a mortgage larger than the conforming limit, which is currently $832,750 for a one-unit home in most areas, with a higher ceiling in designated high-cost areas. Whether you need one depends on the price and on how much you put down. Your lender can tell you which limit applies to the Naperville property you have in mind.
How much do I need to put down on a high-end home?
Lenders commonly quote 10% to 20% or more for jumbo loans, and many also want cash reserves left after closing. The exact amount depends on your credit, income, debts and the lender, so get your own figures from a lender before you start bidding.
Can I find out what my Naperville home is worth without listing it?
Yes. A home valuation is a conversation about what your home would likely sell for and why, and it does not commit you to selling. It is useful if you are deciding whether to sell, buy first, or stay put.